
A townhouse is a residential home that typically shares one or two side walls with neighboring properties while maintaining a separate entrance and individual living space. Most have multiple floors, although designs vary. Depending on the legal structure, owners may hold title to both the building and the land, or own a condominium unit in an attached development.
For homebuyers in the United States, this housing style can offer a balance between the privacy of a detached house and the convenience of lower-maintenance community living.
However, not every attached home comes with the same benefits or responsibilities. Some properties require homeowners association (HOA) fees, others have shared maintenance agreements, and certain developments restrict exterior renovations, parking, or renting.
Understanding these differences is essential before deciding whether this type of home fits your budget and lifestyle.
| Common Question | Quick Answer |
| Is it a single-family home? | It can be classified as an attached single-family dwelling. |
| Does it share walls? | Usually one or two side walls. |
| Does it have an HOA? | Often, but not always. |
| Do you own the land? | Depends on the ownership structure. |
| Is it cheaper than a detached house? | Often, but local market conditions matter. |
| Can it have a private garage? | Yes, depending on the property. |
What Is a Townhouse?
This residential building style consists of individual homes positioned side by side, typically sharing structural walls with neighboring units.
Unlike many apartments, which are arranged vertically within a larger building, traditional townhomes are arranged horizontally. Each residence usually extends from the ground level upward and has its own entrance.
These properties are common in urban neighborhoods, suburban developments, and planned residential communities throughout the United States.
They can range from historic brick homes in established cities to modern three-story properties with attached garages and contemporary interiors.
Key Features of a Typical Townhouse
Although construction styles vary, several characteristics are especially common.
- Shared side walls: Most units connect directly to neighboring residences.
- Private entrance: Residents typically enter from the outside rather than through a shared interior hallway.
- Multiple floors: Bedrooms often occupy the upper levels, while kitchens and living rooms sit below.
- Compact footprint: Vertical layouts provide usable square footage without requiring large parcels of land.
- Outdoor space: Some properties include patios, balconies, decks, or small yards.
- Parking arrangements: Depending on the community, residents may have garages, driveways, assigned spaces, or street parking.
These characteristics are typical rather than universal. Some attached houses have single-story layouts, while others feature three or four levels.
Townhouse vs Townhome vs Row House
The terms townhouse and townhome are generally interchangeable in American real estate listings.
A row house usually refers to a residence within a continuous row of attached houses. The term is particularly associated with older neighborhoods in Philadelphia, Baltimore, Washington, D.C., and other historic cities.
For example, a nineteenth-century brick row house and a newly constructed suburban townhome may have similar shared-wall configurations but dramatically different architecture.
The name alone does not establish how the property is owned, whether it has an HOA, or who maintains shared components.
What Does a Townhouse Look Like Inside and Outside?
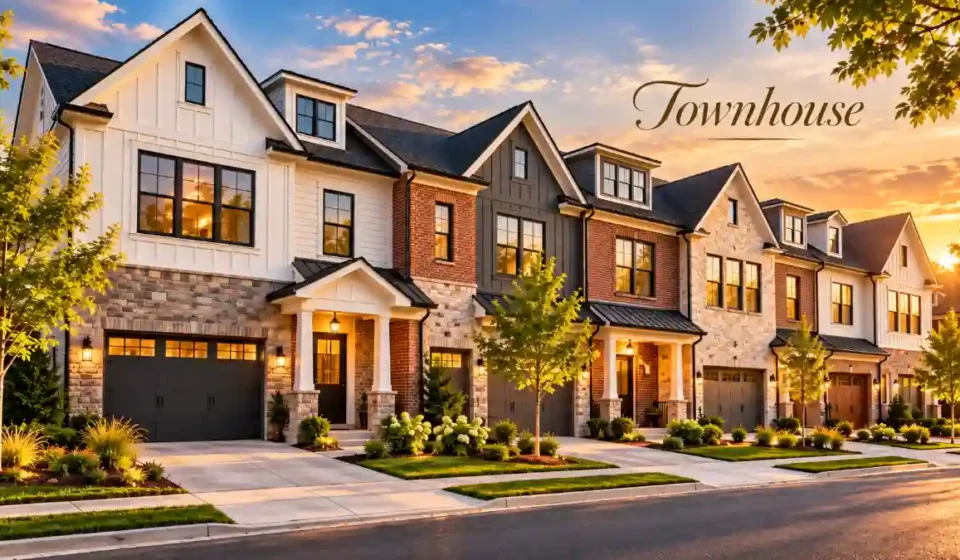
These homes commonly appear as rows of connected residences, each with a distinct front door, windows, and sometimes a small landscaped entrance.
Inside, layouts prioritize vertical space. This can create separate areas for entertaining, working, and sleeping without requiring a large lot.
Common Floor Plans and Layouts
A traditional two-story design may feature a living room, kitchen, dining area, and half bathroom on the first floor, with bedrooms upstairs.
A three-story layout might include:
- Ground floor: Garage, entryway, storage, or guest bedroom
- Second floor: Kitchen, dining room, and main living area
- Third floor: Bedrooms and full bathrooms
Some properties also include basements, rooftop terraces, laundry rooms, or home offices.
The main advantage of this arrangement is functional separation. However, buyers should consider how often they will need to climb stairs throughout an ordinary day.
Interior Units vs End-Unit Townhouses
An interior unit sits between neighboring residences, while an end unit is positioned at the edge of a row.
| Feature | Interior Unit | End Unit |
| Shared side walls | Usually two | Usually one |
| Natural light | Often fewer side windows | Often more side windows |
| Privacy | Neighbors on both sides | Neighbors on one side |
| Exterior exposure | Generally lower | Generally higher |
| Outdoor space | May be smaller | Sometimes larger |
| Purchase price | Often lower | May carry a premium |
Consider two otherwise similar homes listed at $320,000 and $340,000. The more expensive end unit might offer additional windows and a larger side yard.
Those features may justify the difference for a buyer who values natural light and privacy.
However, someone focused on affordability might prefer the interior unit and reserve the savings for furniture, renovations, or emergencies.
Neither option is automatically superior. Construction quality, condition, location, and personal preferences matter more than the unit’s position alone.
Townhouse vs Condo vs Apartment vs Detached House
These housing types are frequently compared because they offer different combinations of space, ownership rights, maintenance responsibilities, and privacy.
The most important distinction is that architectural design and legal ownership are not necessarily the same thing.
| Feature | Townhome | Condo | Apartment | Detached House |
| Shared walls | Usually | Common | Common | Generally none |
| Private entrance | Usually | Sometimes | Sometimes | Usually |
| Multiple floors | Common | Varies | Varies | Varies |
| Ownership | Fee-simple or condo | Condominium ownership | Often rented | Generally land and structure |
| HOA | Often | Generally association-managed | Depends on ownership | Sometimes |
| Exterior maintenance | Owner or association | Often association | Usually landlord when rented | Usually owner |
| Private yard | Sometimes | Sometimes | Less common | Often |
Townhouse vs Condo
A condominium is a legal ownership arrangement rather than a specific building design.
Condo owners generally own a defined unit and share ownership interests in common elements. An association manages responsibilities established by the condominium declaration and applicable law.
A home that looks like a traditional attached house can legally be a condominium.
This distinction affects insurance, financing, exterior maintenance, and certain ownership rights.
Townhouse vs Single-Family Detached House
Detached houses do not share structural side walls with neighboring residences.
They generally provide greater physical independence and may offer larger private yards or more freedom over exterior improvements, subject to zoning, building codes, and any HOA restrictions.
Attached homes may be less expensive in comparable locations and require less outdoor maintenance.
However, shared walls and community rules may limit privacy and customization.
The best comparison includes both the purchase price and ongoing expenses.
Townhouse vs Apartment
Apartments are individual residential units within larger buildings and are commonly rented.
Traditional townhomes generally feature separate outdoor entrances and often have multiple levels.
An apartment renter usually relies on the landlord for major maintenance, while an owner is financially responsible for expenses assigned to the property or unit.
Nevertheless, attached houses can also be rented, and apartments can exist within individually owned condominium developments.
The key difference is not simply the layout, but the ownership and occupancy arrangement.
How Does Townhouse Ownership Work?
Understanding ownership is one of the most important steps when evaluating an attached property.
Two homes may look nearly identical from the street while having different legal structures, insurance requirements, and repair obligations.
Fee-Simple Townhouse Ownership
With fee-simple ownership, the buyer generally owns the building and the underlying parcel of land.
This arrangement provides direct property ownership, but it does not eliminate restrictions.
The property may still be subject to:
- Easements
- Shared-wall agreements
- HOA regulations
- Zoning requirements
- Building codes
- Recorded community covenants
For example, an owner might hold title to the land and residence but still need approval before changing the exterior siding or replacing certain windows.
Condominium-Style Ownership
Some attached homes are legally structured as condominium units.
In this arrangement, owners hold title to their individual units and share interests in common elements according to the condominium declaration.
An association may manage certain roofs, exterior walls, foundations, landscaping, or shared facilities.
However, owners remain responsible for expenses assigned to their units and may need to contribute to shared repairs through regular dues or special assessments.
How to Verify What You Actually Own
Before completing a purchase, examine the deed, title report, recorded plat or survey, declaration, and CC&Rs.
The following table identifies questions to investigate.
| Property Component | Possible Responsible Party | What to Check |
| Roof | Owner or association | Maintenance and replacement rules |
| Exterior walls | Owner or association | Declaration and maintenance provisions |
| Foundation | Owner or association | Structural responsibility |
| Windows | Owner or association | Repair and replacement obligations |
| Yard | Owner or association | Ownership boundaries and landscaping rules |
| Driveway | Owner or shared owners | Easements and maintenance agreements |
| Common roads | Association or another designated party | Community governing documents |
Important: Do not assume the HOA maintains every exterior component.
A real estate attorney or qualified title professional can help clarify unusual ownership arrangements before closing.
Pros and Cons of Living in a Townhouse
Attached-home living can offer affordable access to desirable neighborhoods, but the experience depends on the building, community, and household.
Advantages of Townhouse Living
Potentially lower purchase price: In many markets, attached properties cost less than comparable detached homes because they occupy smaller lots. The difference depends on location, size, finishes, and demand.
Less outdoor maintenance: Smaller yards and shared landscaping can reduce time spent mowing, watering, and maintaining outdoor areas.
Private entrance and functional space: Separate entrances and multiple levels create a more house-like living arrangement than many apartment layouts.
Convenient locations: Efficient land use makes these homes practical in established neighborhoods where detached properties may be expensive or scarce.
Community amenities: Some developments provide swimming pools, fitness centers, playgrounds, walking trails, or maintained green spaces.
Potential energy efficiency: Interior units have fewer exposed side walls, potentially reducing heat transfer. Actual utility expenses depend on insulation, windows, climate, and HVAC equipment.
Disadvantages to Consider
The benefits come with several tradeoffs.
Shared walls may allow sound to travel between neighboring homes. HOA rules can restrict parking, pets, exterior modifications, or renting.
Outdoor space may be limited, and homes with multiple levels can be inconvenient for people who prefer single-story living.
Parking also deserves attention. A property advertised with an attached garage may not provide enough space for larger vehicles, storage, or visitors.
Finally, regular association dues do not necessarily eliminate unexpected expenses. Owners may still face repairs and special assessments.
| Potential Advantage | Possible Tradeoff |
| Less yard maintenance | Smaller private outdoor area |
| Community amenities | HOA dues and restrictions |
| Private entrance | Shared side walls |
| Multilevel living | Frequent stair use |
| Lower initial price in some markets | Additional association expenses |
| Efficient land use | Less distance from neighbors |
Privacy, Shared Walls, and Everyday Noise
Noise deserves more attention than a brief mention in a property listing.
A well-constructed shared-wall assembly may provide substantial sound separation. Poor insulation, gaps around penetrations, or certain floor plans can increase sound transmission.
When viewing a property, visit at different times and listen near bedrooms, staircases, bathrooms, and shared living-room walls.
Ask whether the neighboring home has a garage, entertainment room, or staircase directly against your bedroom.
Also investigate the construction of the party wall if noise is a major concern.
An ordinary home inspection may identify visible deficiencies, but specialized acoustic testing may be necessary to evaluate sound performance.
How Much Does a Townhouse Cost in the USA?
There is no reliable single purchase price that represents every attached home across the United States.
Prices vary widely between cities, neighborhoods, and developments. A smaller property in a high-demand urban location may cost more than a larger detached house in another region.
For that reason, local comparable sales are usually more informative than a national average.
Purchase Price and Local Market Differences
Factors that influence pricing include location, interior square footage, construction age, renovation quality, parking, outdoor space, and community amenities.
An end unit may command a premium because of additional windows or privacy.
However, a well-maintained interior property may offer better value than an end unit requiring expensive repairs.
For example, imagine two listings in the same neighborhood:
- Home A costs $310,000 but needs $20,000 in repairs.
- Home B costs $325,000 and has recently replaced major systems.
Home B may offer better overall value, depending on the quality of the work, financing, HOA responsibilities, and comparable sales.
Review recently closed transactions and obtain appropriate inspections before making a decision.
Monthly Mortgage, Taxes, Insurance, and HOA Costs
The monthly mortgage payment is only part of the homeownership budget.
The Consumer Financial Protection Bureau’s homebuying budget guidance explains that buyers should account for principal, interest, property taxes, insurance, HOA fees, utilities, maintenance, and repairs.
Depending on your financing and ownership arrangement, expenses may include mortgage insurance and supplemental coverage such as flood insurance.
Association dues are usually paid separately from the mortgage servicer, although payment arrangements can vary.
Maintenance, Repairs, and Unexpected Expenses
Association-managed properties are not necessarily maintenance-free.
Owners may remain responsible for appliances, plumbing fixtures, HVAC systems, flooring, interior surfaces, and other components.
In certain developments, individual owners also maintain roofs or exterior structures.
Keep a maintenance reserve based on the property’s condition and your documented responsibilities. Avoid budgeting for the same repair twice if it is already included in HOA-funded work.
Also consider special assessments, insurance deductibles, and potential increases in regular dues.
Townhouse Cost Calculator: Compare Total Monthly Cost
A useful way to evaluate affordability is to calculate the complete monthly housing budget.
\[ \begin{aligned} \text{Monthly Cost} ={}& \text{Mortgage Principal and Interest}\\ &+\text{Property Taxes}+\text{Insurance}\\ &+\text{HOA Dues}+\text{Maintenance Savings}\\ &+\text{Other Housing Costs} \end{aligned} \]
Consider this hypothetical example.
| Monthly Expense | Estimated Amount |
| Mortgage principal and interest | $2,100 |
| Property taxes | $450 |
| Insurance, including PMI if applicable | $140 |
| HOA dues | $225 |
| Maintenance savings | $150 |
| Total monthly housing budget | $3,065 |
That represents $36,780 annually before additional expenses such as utilities if they are not already included.
These are illustrative figures, not current national averages.
Monthly Housing Cost Calculator
Change the example amounts to estimate your expected expenses.
Mortgage principal + interest
Property taxes
Insurance / PMI
HOA dues
Maintenance reserve
Other monthly costs
Estimated monthly cost
$3,065
$36,780 per year
Do not double-count taxes or insurance already included in an escrowed mortgage payment. Upfront down payments, closing costs, and one-time special assessments must be assessed separately.
Understanding HOA Fees, Rules, and Special Assessments
A homeowners association manages community responsibilities defined in its governing documents.
Some associations provide extensive exterior maintenance and shared amenities. Others primarily maintain common roads, landscaping, or neighborhood standards.
What Do HOA Fees Usually Cover?
Depending on the property, association dues may fund landscaping, trash services, snow removal, private roads, recreation facilities, shared utilities, or portions of exterior building maintenance.
They may also contribute to a reserve fund for future major repairs.
Buyers should request an itemized explanation of services instead of assuming that every association provides similar coverage.
What Is a Special Assessment?
A special assessment is an additional charge collected from owners for certain expenses that regular dues or existing reserves cannot adequately cover.
For example, imagine a 30-home community needing $300,000 in unexpected shared roof repairs.
If there are no available reserves or other funding and the expense is assessed equally, each homeowner could face a hypothetical $10,000 charge.
Actual assessments depend on the governing documents, ownership interests, and applicable law.
Fannie Mae’s HOA guidance explains that special assessments can help fund unexpected structural repairs, major replacements, and other community expenses.
HOA Financial Red Flags
Review the association’s financial statements, reserves, and maintenance plans.
Potential warning signs include inadequate reserves relative to future obligations, significant unpaid dues, deferred repairs, unresolved litigation, large insurance deductibles, and repeated assessments.
A low HOA fee is not automatically a bargain if the association is failing to save for long-term maintenance.
Ask whether a reserve study is available and whether the association is funding recommended contributions.
How to Buy a Townhouse: Step-by-Step Checklist
The purchasing process resembles buying a detached home, but association records and legal ownership deserve extra scrutiny.
Step 1 — Establish Your Full Budget
Calculate your comfortable monthly housing budget before viewing properties.
Include your expected mortgage payment, property taxes, insurance, association dues, utilities, repairs, and savings.
Keep enough funds available for closing expenses and emergencies.
Mortgage preapproval can clarify your likely borrowing range, although it does not guarantee final loan approval.
Step 2 — Compare Local Homes and Ownership Types
Review recently sold properties with comparable locations, square footage, condition, and amenities.
Identify whether the home is fee-simple, condominium-owned, or part of a planned unit development.
Compare maintenance responsibilities and association restrictions, not just prices.
Step 3 — Inspect the Property
Hire a qualified inspector and investigate any major concerns through specialists.
Pay particular attention to:
- Roof condition and water intrusion
- Foundation movement and drainage
- Shared-wall and garage separation
- Windows and exterior siding
- HVAC, plumbing, and electrical systems
- Stairways and accessibility
- Driveway dimensions and parking
- Decks, balconies, and exterior structures
Inspecting the individual residence does not necessarily reveal the condition of association-managed structures, so review community inspection and maintenance records where available.
Step 4 — Review HOA and Legal Records
Request the declaration, CC&Rs, bylaws, current budget, financial statements, meeting minutes, insurance information, and reserve study where available.
Check for pending assessments, rental restrictions, litigation, and planned repairs.
Fannie Mae specifically advises condominium buyers to investigate community physical condition, financial stability, insurance coverage, and potential legal issues.
Step 5 — Confirm Financing and Closing Requirements
Tell your lender how the property is legally classified.
Condominium ownership may involve project-level reviews, including association finances, insurance, and building condition.
Before closing, verify your loan terms, title arrangements, insurance, association obligations, and final cash requirements.
Review the Loan Estimate and Closing Disclosure, including escrow and estimated costs. The CFPB Loan Estimate guide explains how these expenses appear in mortgage disclosures.
7 Townhouse Buying Mistakes That Can Cost You Money
An attractive exterior and updated interior do not guarantee a financially sound purchase. The following mistakes can create unexpected costs or long-term frustration.
1. Assuming the HOA Covers Every Repair
Some buyers believe association dues automatically cover roof replacement, exterior painting, plumbing, and structural repairs.
In reality, responsibilities vary.
How to avoid it: Request the maintenance responsibility chart or governing documents. Verify who pays for roofs, windows, foundations, siding, shared walls, and major utility systems.
2. Ignoring Special Assessments
Regular monthly payments do not eliminate the possibility of additional assessments.
A community with aging structures or insufficient reserves may require substantial owner contributions.
How to avoid it: Review the reserve study, budgets, meeting minutes, major repair plans, and assessment history before purchasing.
3. Not Verifying Land Ownership
A property may look like an ordinary attached single-family house while legally being a condominium unit.
This can affect title rights, insurance, maintenance, and financing.
How to avoid it: Examine the deed, recorded declaration, survey or plat, and title documentation with a qualified professional.
4. Viewing the Home Only Once
A quiet weekday showing may not reveal evening parking problems, neighboring noise, or heavy weekend activity.
How to avoid it: Visit at different times when possible. Check street traffic, guest parking, shared outdoor areas, and noise near common walls.
5. Underestimating Stairs
A three-story layout might seem appealing during a short viewing.
However, carrying groceries upstairs, transporting laundry between floors, or managing mobility limitations can become inconvenient.
How to avoid it: Imagine a typical weekday, including parking, cooking, laundry, bedtime, and trips outside.
Consider whether the property will remain practical if your mobility needs change.
6. Overlooking Insurance Gaps
The association’s master policy may not cover all interior improvements, personal belongings, or owner responsibilities.
Certain losses may also involve substantial deductibles or exclusions.
How to avoid it: Review the master policy and ask an insurance professional about individual coverage, loss assessments, flood risks, and other applicable protections.
7. Focusing Only on the Asking Price
A lower-priced home with high dues, deferred repairs, or expected special assessments may cost more than a slightly more expensive alternative.
How to avoid it: Compare total housing expenses and property condition, not just mortgage payments.
The Townhouse Reality Check
Before making an offer, complete this simple assessment.
| Question | What to Confirm |
| What do I legally own? | Deed and ownership classification |
| Who pays for major repairs? | Maintenance responsibility documents |
| What is the true monthly cost? | Mortgage, taxes, insurance, HOA, utilities, and maintenance |
| Are additional assessments likely? | Reserve study and planned projects |
| What restrictions apply? | Parking, pets, rentals, and renovations |
| Does the layout fit my lifestyle? | Stairs, storage, privacy, and outdoor space |
| Are any major concerns unresolved? | Inspection, financing, insurance, or title issues |
If several answers remain unclear, investigate them before allowing the applicable contract deadlines to pass.
Is a Townhouse a Good Investment?
Attached housing can be a reasonable long-term investment, but future performance depends on the property and local market.
Purchase price, location, financing costs, maintenance obligations, and community financial stability all influence ownership outcomes.
Resale Value and Appreciation Factors
Potential resale performance is affected by:
- Neighborhood demand and local economic conditions
- Comparable recent sales
- Property condition and renovation quality
- Parking availability
- Outdoor space
- HOA fees and association finances
- Nearby housing supply
- Buyer preferences and accessibility
An end unit may sell for more than an interior unit in certain developments, but appreciation is not guaranteed.
Buyers should also consider selling expenses, years of ownership, and ongoing costs when evaluating potential returns.
Renting Out a Townhouse
Some homeowners eventually turn their properties into rentals.
Before purchasing with this goal, verify whether the association permits leasing. Certain communities impose rental caps, minimum lease terms, tenant registration requirements, or restrictions on short-term rentals.
Estimate net cash flow after mortgage payments, taxes, insurance, HOA dues, repairs, vacancies, and property management.
For example, earning $2,500 monthly in rent does not automatically produce a profit if combined housing expenses approach or exceed that amount.
Rental property taxation, insurance, and financing requirements may also differ from those of an owner-occupied residence.
Is a Townhouse Right for You?
The best housing choice depends on how much you value privacy, affordability, location, maintenance convenience, and freedom to modify your property.
Best Fit for First-Time Buyers, Families, and Professionals
Attached homes may appeal to first-time buyers who want their own entrance and manageable outdoor responsibilities.
Busy professionals may appreciate locations near employment centers, shopping, and transportation.
Families can benefit from separate bedrooms, additional living space, and access to community amenities.
For example, a family with two children might choose a three-bedroom property with an attached garage and nearby playground rather than a similarly priced apartment-style condo.
However, the number of stairs, shared-wall noise, school options, and outdoor space should still be evaluated.
Read More: What Is a Townhouse
When Another Property Type May Be Better
A detached house may be preferable for buyers seeking a large yard, more distance from neighbors, and greater exterior independence.
A single-level home or accessible condo may be more practical for people who want to minimize stair use.
Renting may suit individuals who expect to move frequently or prefer not to manage major ownership expenses.
| Your Priority | Potential Suitability |
| Lower yard maintenance | Often a good fit |
| Private entrance | Usually a good fit |
| Large private yard | Often less suitable |
| Maximum sound privacy | Depends heavily on construction |
| Minimal stairs | Often less suitable |
| Community amenities | Can be a good fit |
| Exterior customization | May be restricted |
| Predictable expenses | Requires HOA and maintenance review |
Before deciding, answer five questions:
- Am I comfortable living next to neighbors with shared walls?
- Can I comfortably use the property’s stairs every day?
- Do the HOA rules match my lifestyle?
- Can I afford both regular costs and unexpected repairs?
- Would I prefer more land and greater independence?
If several answers raise concerns, compare other housing types before making an offer.
Townhouse FAQs
Is a townhouse considered a single-family home?
Yes. An attached property can be classified as a single-family residence even when it shares structural walls with neighboring homes. However, legal classification varies by jurisdiction and ownership structure. Some properties are individually owned attached homes, while others are legally organized as condominium units.
Do you own the land when you buy a townhouse?
It depends on the ownership arrangement. Fee-simple ownership generally includes the building and underlying parcel of land. Condominium ownership generally includes a defined unit and shared interests in common elements. Review the deed, title documents, and recorded declaration to establish the precise ownership rights.
Does every townhouse have an HOA?
No. Many newer developments have homeowners associations, but some older attached properties do not. Even without an HOA, owners may still have shared-wall agreements, easements, and maintenance obligations. Buyers should verify the property’s legal arrangements rather than assuming an association exists.
Are townhouses cheaper than detached houses?
They are often less expensive than comparable detached properties within the same local market, but this is not guaranteed. Location, square footage, condition, amenities, and land value affect pricing. HOA dues, insurance, taxes, and repairs must also be considered when comparing total ownership costs.
Can a townhouse be legally classified as a condo?
Yes. The architectural style and legal ownership structure are separate concepts. A multistory attached residence with a private entrance can legally be a condominium unit. The recorded declaration and governing documents establish ownership boundaries, association responsibilities, and common-element rights.
Who is responsible for replacing a townhouse roof?
Roof replacement responsibility depends on the governing documents and legal ownership structure. In some communities, individual owners handle roof repairs and replacement. In others, the association maintains shared roofing systems. Confirm responsibilities through the declaration, maintenance provisions, and association records.
Are townhouse walls soundproof?
Not necessarily. Sound transmission depends on wall construction, insulation, building design, workmanship, and neighboring activity. Some properties provide good acoustic separation, while others allow noticeable noise transfer. Visiting at different times and investigating wall construction can help buyers assess potential concerns.
Can you renovate or expand a townhouse?
Many interior renovations are possible, but major structural work, exterior changes, and additions may require permits or association approval. Shared-wall agreements, zoning rules, lot boundaries, and building codes may also restrict modifications. Always verify the applicable requirements before beginning a project.
Is an end-unit townhouse worth paying more for?
An end unit may justify a premium for buyers who value additional windows, greater privacy, or more outdoor space. However, purchase price, condition, utility expenses, and nearby comparable sales should guide the decision. A well-maintained interior unit can offer better value for some buyers.
Are townhouses good for first-time homebuyers?
They can be a practical option for first-time buyers seeking private living space with potentially less yard maintenance than a detached home. However, HOA finances, shared-wall conditions, stairs, ownership rights, insurance obligations, and full monthly expenses should all be reviewed before purchasing.